of (93)

Bank of America shortsale in Equator

"Property has been successfully imported into the application. Please check your Workflow for any tasks assigned to you for this property. Thank you."

This is the third time I have entered this property in Equator.

The first time, the buyer could not perform. Although they have created a system to simplistically add a new buyer this was "hard decline", needless to say I was required to start over.

Third time's a charm, let's see how we do!

Read more…

Columbus Ohio is Buyer Friendly

Columbus Ohio is one of the top 10 cities in the United States in which to buy a house, according to http://www.NerdWallet.com, a website designed to provide financial advice and data for young people. The site considered three criteria - availability of homes, cost of living and anticipated growth (measured by population & job growth). Columbus just made the cut at No. 10with these coments "Columbus is a great place to settle down and buy a home, with its low cost of living. This college town (it's home to The Ohio State University) has a laid-back Midwestern vibe." Topping the list was Fort Worth, Texas, followed by Charlotte, N.C. and San Antonio. Indianapolis, at No. 8, was the only other Midwestern city on the list.

Read more…

Bank of America Short Sale

Bank of America Short Sale

Is your mortgage or mortgages held or serviced by Bank of America? Are you considering a short sale or do you have questions about the short sale process and how it affects your potential success of a short sale?

Bank of America has a few different short sale programs to help homeowners contemplating short selling their house. Plus, you may receive between $2,500 to $30,000 in short sale incentives, depending on your specific situation.

To find out details of Bank of America's Short Sale Incentive Programs <--- Just Click Here. Or call us and let's discuss your unique situation:

---------

Call Now: (888) 9-List-It.

That's (888) 954-7848.

Read more…

Thousands of homes Foreclosed; Can you afford a Risky Loan?

The adjustable rate mortgage has been around for a number of years and it has helped a number of people afford the purchase of their first home. However, in the late 90’s and early part of the 2000’s some people took advantage of the low rates offered by ARMS and got in over their head. Before buying a home people should really look at all the factors involved with an adjustable rate loan and make sure it is right for them.

Fixed Period Varies

Dollar-House-300x300.jpg?width=300
photo credit: nikcname via photopin cc

The vast majority of current ARM’s offer a well-defined period in which the interest rate is fixed. The defined period typically lasts from 3 to 7 years and can be as long as 10 years. After this defined period the interest rate will adjust based on the index used to calculate the interest rate.

Some people have well defined plans and can use the fixed period for meeting their goals. For instance, a military couple that has an assignment to a particular area could purchase a home using a 5 year ARM and use the time to live in the home with no worries about a change in interest rate.

However, people that are just looking at the low rates of the ARM’s and “hoping” that their income will rise in future years are taking a big gamble.

Rates Will Rise

Years ago when the ARM was first introduced it was always explained the same way. When the market took a dip the interest rate would lower accordingly and the opposite would happen when the market improved. However, the last few years have seen nothing but historically low rates. Getting an adjustable rate loan now ensures one thing; the interest rate will rise once the fixed period ends. The current rates cannot get much lower.

Thankfully, an adjustable rate mortgage will have some safeguards to protect borrowers. The amount of increase for the rate is usually capped each year as well as a cap for the duration of the loan. For instance, most ARM’s will not adjust more than 1% in one year and no more than 5% or 7% over the course of the loan. However, a 5% increase in rate on a $250,000 loan can increase a loan payment by over $700. Keep in mind that when the interest rate adjusts the new payment is factored over the remaining loan term. This can drive up the payment as well.

Plan Accordingly

All of this information points to one simple fact. People considering an adjustable rate loan need to plan accordingly. You should have some type of exit strategy in mind, whether it is selling or refinancing or paying off the loan in order to avoid some potentially hazardous conditions in the near future.

This communication is provided to you for informational purposes only and should not be relied upon by you. Rock Realty is not a mortgage lender and so you should contact a lender directly to learn more about its mortgage products and your eligibility for such products.

Related posts:

  1. WHEDA Home Loan Mortgage Rates at Historic Low I receive daily updates on current mortgage rates in the...
  2. Rising Rents Provide More Reasons to Buy a Home Rising Rents Provide More Reasons to Buy a Home The...
  3. New WHEDA Loan Programs Are you a first-time buyer? Do you want an affordable...
  4. 7 Key Questions to ask about your Mortgage Key Questions to Ask About Your Mortgage This week I...
  5. Fannie Mae: Qualifying for interest-only loans tougher Thanks to the Wisconsin Realtors Association for bringing this to...
Read more…

If you are at risk of foreclosure, you might want to know what the consequences are in the event that it happens to you. The evident and inevitable effect a foreclosure has is the ding on your FICO score as well as the foreclosure stamp on your credit report. This will make it very difficult for you to obtain any credit or even find alternative housing or employment. However, is that all to the negative effects of a foreclosure? Let’s explore deficiency judgments after foreclosure.

Recourse vs Non-Recourse State

In every state, there are different foreclosure laws regarding whether lenders can pursue you for the remaining balance after a foreclosure or not. Check HERE to see if your State is a recourse or non-recourse state.

If you are in a recourse state, then it is possible for your lender to sue you and obtain judgment for the remaining balance owed. If a judgment is entered against you, they may be able to garnish wages and/or seize any non-exempt property you owe. Although not likely, they may even be able to seize your vehicle but this of course depends on the state specific laws. It might be worth it to do a bit of research on the subject.

If you are living in a non-recourse state, the foreclosing lender cannot pursue but you are not off the hook yet!

Any otherlenders (2nd mortgages or even 3rd or 4th) ARE able to pursue you for the remaining balance.

We at seattleshortsaleblog have received numerous requests for help in dealing with subordinate lienholders whom after the home was foreclosed on, is now pursuing the homeowner via threatening judgment, judgment, or the popular strategy, selling off the debt to collection companies.

We feel it is better to pursue a short sale, and get a deficiency waiver prior to closing the sale. Those 10 words on the approval letter, “we hereby release our rights to collect a deficiency judgment” (or verbiage similar) are VERY IMPORTANT and in our opinion, better than hoping the lender will not come after you after foreclosure.

Hope this helps

Peter


Full Article Here: www.seattleshortsaleblog.com
Feel free to share the articles on my blog with homeowners in your area!

Read more…

While prices are rising in the Silicon Valley there are still homes that are underwater and you may need to short sale your South San Jose home. If this is the case, don't wait!

Bank of America has instituted some new policies which can have a major influence on your South San Jose short sale.

Co-operative Short Sales: Bank of America has a program where they will let you know ahead of time how much they are willing to accept for you South San Jose home in a short sale. Once you agreed to do the short sale they would put a hold on foreclosure activity and give you some money at close of escrow.

The new policy is that there will be no holds on foreclosure until the offer is fully accepted by Bank of America. What this means is that if you can not make your payments  on your South San Jose home and want to short sell you can not wait. You will not be allowed to stay in your home for months trying to modify your loan and trying to get a new job. Once the notice of default has been recorded you will have 3 months to get your South San Jose home sold as a short sale before the notice of trustee sale is recorded. At that point you have another 3 weeks before foreclosure on your South San Jose home.

As any real estate agent familar with south San Jose short sales knows, they take time for approval. Even a Bank of America co-operative short sale can take time. 4 months is not unheard of to obtain approval on a South San Jose Short Sale, so if you can not make your payments, do something or you could lose your home to foreclosure.

If you have any questions about Short Sales in Santa Clara or San Mateo County please feel free to contact me.

Marcy Moyer

Keller Williams Realty

www.marcymoyer.com

marcy@marcymoyer.com

D.R.E. 01191194

650-619-9285

Read more…

This is common question asked by our clients here in Texas. In this article, I want to give you some things to think about if your client is asking this question..  In deciding whether you should or should not recommend that your client stop making your mortgage payments, these are things we have learned from experience and face every day with our clients.

To begin, you should never recommend that someone stop making a mortgage payment. Its not ethical and lenders would not be happy.  However, you can tell you client what happens if they stop making the payments during a short sale.
 
What happens when a client stops making the mortgage payment:
 
When you are trying to do a short sale  the bank is looking for a hardship, and this can be a number of things. A hardship can be a job loss, Income reduction, forced relocation, Illness or a divorce. If a client continues to make the mortgage payments the bank is less likely to accept the short sale. A lot of investors are rejecting short sales if the mortgage is current. We have had lenders who will tell us just by looking at the file that our clients do not “qualify” because their loan is current.
 
A lot of our clients struggle with this fact because they do not want the missed payments to affect their credit. Most likely if they are in the situation of a hardship their credit has already been affected in some way. If they continue to make the payments the bank may assume they can afford the mortgage and will not consider the “hardship”. The bank will not make the file a priority as they are not in “default”. This is a hard concept to understand as you would think the bank would want to continue to receive payments and still work with struggling homeowners. Unfortunately that is not the case, in order to be considered for most short sales, banks will only review if they are in default. Some banks are now requiring the homeowners to be at least 30-60 days behind on their mortgage. Although this goes for the majority of the banks, there are still a small few that will work with homeowners without being behind.
 
If your client stops the mortgage payment, they need to understand it maybe impossible to "catch back up".  I've had a couple of clients say they plan on stopping the mortgage payments to get the bank to do a short sale and if the short sale is not approved they will get the payments caught back up. 

After a client has missed several payments, the late fees and penalties can be overwhelming. This can make it outside the clients financial ability to actually catch back up.

Bottom line:  Missing payments maybe necessary to get a short sale approved; however, it will impact their credit report and it make cause a foreclosure if the short sale is not approved.

Read more…

Front-Yard-e1357247853719.jpg?width=300We are happy to announce the closing on another one of our short sale listings, this time in Madison, WI! This was a Bank of America negotiated short sale. Bank of America has made many changes to make their short sale process easier and more efficient. Short sale transactions can be complex, but if you have an experienced Short Sale Realtor® the process is much more manageable.


This was a beautiful home, at a great price that the new owners are sure to enjoy! If you are thinking of selling or buying a short sale home in Wisconsin, our short sale specialists would be happy to assist you. Give Rock Realty a call at 608-921-8536.


Is a Short Sale right for my situation??

If you are considering the possibility of a short sale for your home and have further questions, feel free to visit the page below:

Is a Short Sale right for My Home?

Read more…

Bank  of America has entered into an $11.6 billion settlement to end Fannie Mae's  claims that the bank improperly sold it mortgages that later soured, and to  resolve problems with foreclosures,  the companies said.

The settlement is a major step for Bank of America toward resolving claims  from investors who want the bank to buy back loans that its Countrywide  Financial subsidiary sold to them during the housing boom, many of which later  went bad.

The agreement largely covers the $11.2 billion of claims that  government-owned finance company Fannie Mae had against the bank, which  represented about 44 percent of the bank's total pending claims at the end of  the third quarter.

Bank of America, which bought Countrywide in 2008, still needs court approval  for an $8.5 billion settlement with private investors and is locked in  litigation with insurer MBIA Inc over mortgage-related claims.

The settlements, other charges, and a series of asset sales the bank also  announced Monday will result in Bank of America posting only a small profit for  2012's fourth quarter. Bank of America is paying $3.6 billion to Fannie Mae and  buying back $6.75 billion of bad loans from the mortgage company to clear up all  claims that government-owned Fannie Mae had made against the bank. Bank of  America is buying the loans for the value of their outstanding principle, and  will immediately record a loss on them.

Fannie Mae and its sibling, Freddie Mac, essentially buy mortgages from banks  and package them into bonds for investors. But in the mortgage boom, banks sold  loans to the two companies that Fannie Mae and Freddie Mac say should never have  been sold, because for example, borrowers had misstated their income. The two  mortgage finance companies are pushing banks to buy back the loans.

Bank of America said most of the repurchasing settlement would be covered by  reserves, and another $2.5 billion, before taxes, that it set aside in the  fourth quarter.

A separate settlement over foreclosure delays will result in Bank of America paying $1.3 billion to Fannie Mae, the  mortgage company said. Bank of America had already set aside money to cover most  of that, but took another $260 million charge in the fourth quarter to cover the  balance.

Bank of America also sold the rights to collect payments on about $306  billion of loans to Nationstar Mortgage Holdings and Walter Investment  Management Corp. Nationstar is paying $1.3 billion for the right to service some  $215 billion of loans, while Walter Investment is paying $519 million for the  right to service about $93 billion of mortgages.

Reuters first reported on Friday that Bank of America was talking to  Nationstar and Walter Investment.

Bank of America is eager to reduce expenses in its mortgage servicing unit,  where costs have ballooned as the bank has hired staff to work with customers  behind on payments and those seeking alternatives to foreclosure such as Bank  of America loan modifications and short sales. The unit now has nearly  42,000 employees, about 15 percent of the bank's total workforce.

At the end of December, Bank of America had 775,000 home loans that were  delinquent by 60 days or more, down from 936,000 loans at the end of September.  After the latest sale, the bank said this number will decline substantially.

The No. 2 U.S. bank by assets has lagged peers in recovering from the  financial crisis largely due to losses from its disastrous Countrywide  acquisition. The bank has paid more than $40 billion to settle lawsuits and to  buy back soured loans.

Two years ago, Bank of America reached settlements with Fannie Mae and  Freddie Mac over loan repurchase requests. The pact with Freddie Mac covered all  outstanding claims, but the agreement with Fannie Mae covered only claims that  were already in the works. Fannie Mae later began sending new claims to the bank  over loans originated during the housing boom, spurring the dispute between the  two companies.

Bank of America said Monday it will take an additional $2.5 billion expense  in the fourth quarter for a settlement with federal regulators over improper  foreclosures as well as other mortgage-related matters. The results will also  include a $700 million charge related to the value of the bank's debt and a $1.3  billion tax benefit.
Connect with us

READ THE ORIGINAL ARTICLE HERE (Reporting By Rick Rothacker; Editing by Dan Wilchins, Maureen Bavdek and David Gregorio)
Read more…

I was reading about short sales, as I do every Sunday morning on a great site for short sale information Short Sale Superstars. There was a discussion about a Bank of America Short Sale that had been approved, and then denied after the approval, a few days before closing. The reason:

The seller was a real estate broker and the listing agent works for the seller. The buyer used the listing agent to represent her.

Surprise Surprise, B of A said this is not an Arm's Length Transaction and rescinded the approval.

Blossom Valley Short Sale


There are multiple things wrong with transaction so let me see if I can organize the problems coherently.

1. All short sales must be an Arm's Length Transaction and an affidavit needs to be signed by all parties saying they are not related to each other in any way. The listing agent works for the seller so that is not arms length.

2. The seller may be offered a closing incentive by the bank, but is not allowed to receive any money from the buyer. Since the buyer is using the the listing agent who works for the seller and would have received commission for the sale, a portion of which would go to the broker, then the seller is getting money from the buyer.

3. Again, since the listing agent works for the seller and would get commission from the sale, a portion of which would go to the broker, the seller would be receiving money from the sale outside of the closing incentive.

4. The buyer has agreed to a dual agency and is entitled to the information that the listing agent works for the seller and that this can cause potential problems with The Arm's Length Transaction.

I do not know if the seller was trying to pull something over on the bank, or if he was just not familiar with short sales but this was totally avoidable.

Buyers: get your own agent to represent you.

Sellers: If you are a broker, get a different company to represent you. If you are an agent, get another agent to represent you, not your broker, and ask the bank if it is ok to be represented by someone else in your campany first, not after you are about to close.

If you have any questions about buying or selling a short sale in Santa Clara or San Mateo County please feel free to contact me.

Marcy Moyer

Keller Williams Realty

www.marcymoyer.com

marcy@marcymoyer.com

650-619-9285

D.R.E. 01191194

Read more…

I have to say that I am EXTREMELY pleased that the Mortgage Debt Forgiveness Relief Act has been extended for another year. If you are a homeowner in distress this is not the time to sit back and relax because there is not guarantee that this will be ar135749210826744.jpg?width=250extended after the end of this year. This is the time for YOU to take ACTION...AND it is the BEST time for YOU to take action. 

In November, I had given numbers of homeowners in default throughout the country. These, of course, were statistics up to the month of November 2012. I was especially shocked by the last statistic of close to 2 million homeowners were in Foreclosure status. That is a great concern and can be avoided by the homeowners taking action, Real Estate Agents getting the word out to the homeowners. 

There are many programs in place to help homeowners either stay in their home (if the numbers make sense) through a loan modification or to exit gracefully with a Short Sale. If a homeowner chooses the latter they are sure to reap the some of the following benefits of selling their home: 

  • MORTGAGE DEBT RELIEF ACT: This act will allow homeowners to exclude the forgiven debt on the principal residence from income. 
  • THERE IS NO COST TO THE HOMEOWNER: The commission for the sale of the home is paid through the lender. 
  • YOU DO NOT HAVE TO BE BEHIND IN YOUR PAYMENTS: Depending on your lender, you may be able to move forward with a short sale if you are not behind on your payments! This is huge...as long as you can show a hardship, you may be able to complete a short sale, save your credit, and move on to something better and more affordable.
  • CALIFORNIA HOMEOWNER BILL OF RIGHTS: Sellers will benefit from the Single Point of Contact (SPOC) and th end of Dual Tracking. So, the lender/investor can not foreclosure on homeowner in the midst of them performing a short sale (this also applies for a loan modification).
  • RELOCATION FEE: Some lenders are offering up to $35,000 for homeowners and tenants to exit the home gracefully and keeping the home is saleable condition. 
  • COMMUNITY GROWTH: Although, property values have dropped considerably. Completing a short sale keeps the home from being vacant and/or abandoned. Abandoned homes will continue to bring down the value of the home and the community. 
  • GRACEFUL EXIT: The beauty of a short sale is that, although sellers may take a hit on the credit (If they are late on their payments), they will still have the opportunity to purchase again in 2-3 years (as long as they are continue to save and  work on their credit). Not to mention that they have helped the community, agent, lender, and investor.

The bottom line is that homeowners need to open their communication to receive the benefits from the help that is available. 

Read more…

As part of the fiscal cliff deal, Congress extended the cancellation of mortgage debt relief provision, also known as the Mortgage Debt Relief Act for one year, through the end of 2013. President Obama is expected to sign the legislation into law shortly.

The law – which was set to expire at the end of 2012 - is crucial to foreclosure mitigation efforts such as principal forgiveness and short sales. Normally, U.S. law decrees that when a lender forgives all or a portion of a borrower’s debt, the forgiven amount is considered taxable income for the borrower. This is known as Cancellation of Debt (COD) Income and must be included in a taxpayer’s gross income.

This Act, however, created an exception to this rule under the U.S. Tax Code. The Mortgage Forgiveness Debt Relief Act allows homeowners who received principal reductions or other forms of debt forgiveness to not pay taxes on the amount forgiven. The amount extends up to $2 million of debt forgiven on the homeowner’s principal residence.

For homeowner’s to qualify, their debt must have been used to “buy, build, or substantially improve” their principal residence and be secured by that residence. The law, which was passed in 2007 with a five year sunset provision, will now be in effect until January 1, 2014.

If you're facing foreclosure you're facing some very important  decisions. We want you know you're not alone and we are here to help  with any questions you may have to assist you in making the best decisions for  your situation. There is no charge for this service and we are happy to help! We  offer confidential and professional real estate advice.

The Opland Group Specializes in Real Estate Sales, Luxury Home Sales, Short  Sales in; Bexley Columbus Delaware Downtown Dublin Gahanna Grandview Heights Granville Grove City Groveport Hilliard Lewis Center New Albany Pickerington Polaris Powell Upper Arlington Westerville Worthington

Read more…

Bank of America is Offering To Pay Off Second Mortgages?|Carson|  Leesa Hammond

As part of the National Mortgage Settlement, Bank of America announced on Friday that it is in the process of  mailing approximately 150,000 letters to their pre-qualified homeowners offering to cancel their second mortgage.  The intention of Bank of America is to help improve the financial position of the homeowner by decreasing their monthly payment obligations and potentially creating an equity position in the property. Bank of America began mailing these notices to their qualified borrowers in July and will continue through December 2012. The letters will notify eligible homeowners that the full balance of the second lien mortgage will be forgiven and the lien removed and cleared.  The borrower does have the option to call the bank to decline the offer within 30 days of receiving the letter.    Hmm... isn't that interesting.

What is the criteria to have the second mortgage forgiven?

  • Mortgage must be owned and serviced by Bank of America
  • Eligible borrower must be severely delinquent
  • Second mortgage must meet certain threshold of delinquency or property value criteria
  • Does not matter who owns and services the first lien mortgage
  • Only borrowers who receive the mortgage elimination letters are eligible

Downsides for the borrower:

  • Unless you received second lien mortgage forgiveness letter, customers can not request to be part of the program
  • If the borrower is currently in foreclosure the elimination of the second mortgage will not stop the foreclosure from proceeding
  • Possibility of a tax liability, there are some exceptions  – always check with your tax advisor

Good news:

  • Bank of America will report the account paid and closed on the borrower’s credit report
  • Bank of America will NOT pursue the homeowner for a deficiency judgment

Bank of America will continue to help customers who are in need of assistance with their mortgage. Contact Bank Of America's customer call center or by visiting them on the web to find out about other available programs.

mrsleesa@gmail.com

Leesa Hammond

Century 21 Amber

(310) 890-4439

Bank of America is Offering To Pay Off Second Mortgages??? | Carson| Leesa Hammond

Bank of America is Offering To Pay Off Second Mortgages??? | Carson| Leesa Hammond

Bank of America is Offering To Pay Off Second Mortgages??? | Carson| Leesa Hammond
Read more…

I am so excited about this news! I know, it doesn't take much for me to get excited, but this is really big news in my opinion.

Up until now if you were involved in a Silicon Valley Bank of America Short Sale they did not take electronic signatures. This would have been ok if the bank could sit with you in your conference room and look at the offers. We all know this does not happen and the paperwork will often be faxed several times before B of A gets to see a document. Since they cannot accept illegible documents it made things harder for the participants.

Also, despite the sometime lengthy process of a short sale, Bank of America will often say they need a document now, and not being able to get electronic signatures is sometimes tough.

Now, for any new short sales, you can send all documents with electronic signatures. This makes me very happy. As a Silicon Valley Short Sale Specialist anything that can make a short sale more efficient is ok with me.

So if you have any questions about short sales in San Mateo or Santa Clara Counties please feel free to contact me.

Marcy Moyer

Keller Williams Realty

www.marcymoyer.com

marcy@marcymoyer.com

650-619-9285

D.R.E. 01191194

Read more…

Do you have a client walking the fine line between foreclosure and a short sale? They may have several questions regarding their predicament that you might not know the best way to answer. The good news is that’s what we are here for! We have compiled a few key points that should be made to a wavering client regarding their decision to short sale or not.

First, let’s start with the definition of a short sale:

In simple terms, a short sale is a graceful exit from an underwater mortgage. The lender will agree to sell the home for less than what is owed on the mortgage.

Secondly, what are the perceived advantages of a short sale?

  1. Credit - If a homeowner decides to short sale instead of foreclose, they can become a homeowner again far quicker.  In fact, updated Fannie Mae guidelines assist homeowners in qualifying for loans just 2 years after their short sale. If a foreclosure is on record, it could take as long as 7 years to purchase again.
  2. Short sellers could obtain additional time in the property - During a short sale, the homeowner could have more time to plan for what’s to come. Since the average short sale takes between 60-90 days, there isn’t a rush to immediately find a new residence. With a foreclosure, you could have as little as 30 days.
  3. Short Sale Cash at closing / Relocation Assistance – There are many updated government short sale programs available and designed to assist the homeowner in need. Bank of America has recently begun to offer pre-approved homeowners up to $30,000 in assistance. We’ve also had Chase and CITI offer homeowners $12,000 - $30,000 as a cash incentive to the homeowner short selling their property. There is also the HAFA (Home Affordable Foreclosure Alternatives) program that is there to assist qualified homeowners with a relocation assistance of up to $3,000.
  4. Mortgage Debt Forgiveness Act– There is the Debt Forgiveness Act of 2007 which may forgive the homeowners of paying the taxes associated with the cancelled debt of selling the property short. This is a question for a Certified Public Accountant.  Click here to see the Mortgage Debt Relief Act of 2007 as described by the Internal Revenue Service (IRS)

Lastly, what could be the perceived disadvantages of a short sale?

  1. Credit - If a homeowner decides to take the route of a short sale, their credit score may be impacted due to the late mortgage payments and/or the reporting of the account being paid in less than full. However, it typically won’t be impacted nearly as much as a foreclosure.
  2. Mortgage Debt Tax Liability – The seller may be responsible for additional taxes if they choose to short sell. If the lender agrees to the short sale, there may be a liability to pay taxes on the debt forgiven. It is important to speak with a tax attorney or professional regarding this matter.
  3. Deficiency Judgments - In some states, the lender may be able to come after the homeowner for the deficiency amount.  In the state of California, for instance, there are Senate Bills that protect California homeowners who decide to short sale their property.  (Senate Bill 931 and Senate Bill 458). Again, it is important to speak with a tax attorney or professional regarding this matter.

At Short Sale Experts INC, we can answer these questions (minus the specific legal or tax questions) plus many more! We are here to help – our name says it all!

888-SHORT-20

Read more…

12433928462?profile=originalMy reservations about B of A's COOP short sale program may be easing here in Palm Springs Valley of California.  The only drawback I could see was that the appraisals kept coming in over market, and that dragged out the Listing time.  However, there are reductions scheduled for every 21 days so with this Short Sale without an offer, it seemed a perfect fit.

It took about 3 weeks for B of A to do their BPO, and assign a Listing Number to the property.  I had a number in my head that I knew would generate activity, and the number I got last week was actually approx. $3,000 LOWER than my number!  Great..off to a solid start.

I listed the Condo at Palm Lake in Palm Desert at 5:30 a.m., and had a cash offer by 5 pm..and the cash offer is about $2,000 OVER their List Price.  So, in this case, it was the correct number.

I have uploaded everything to Equator and my contact tells me they will review it early next week and let me know if we are golden to open Escrow and proceed to close.

The lower price points seem to be easier for the Investors to assign numbers to.  As you move up in values, their suggesst list prices get a little skewed, but that's to be expected I guess because not as many are SOLD!

Oh..best part?  The Condo is selling for approx. $52,000 and B of A is allowing $5,000 relocation fees to the Seller!  She's thrilled since she has lost a ton of money from what she paid in 2007. 

Choose an experienced Short Sale List Agent.  Certified, and experienced with lots of different Lenders..references provided upon request.  FREE consultations on your many options..760-285-3578.

Read more…

Anyone with experience in short sales and REO's know the bank requires proof in writing that the buyer has the necessary funds for the purchase of the property. If the buyer is paying cash I have always advised them to obtain a letter from their bank stating they have the necessary funds for the transaction.

In a recent short sale where I had the listing, the buyer submitted a letter from his bank signed by the Vice President of Banking which included his contact number and email.

Short Sale Proof of Funds

The negotiator with the bank would not accept the letter as proof of funds and asked for a copy of the buyer's account statment. His reason was the wording "access to cash currently on deposit". He said the buyer could move these funds from this account into another account at any time. I responded by saying the buyer could still move funds from an account after he gets a copy of the bank statement. He simply said "A bank statement would be different".

I understand an actual copy of the bank statement is a harder proof of funds, but if there is any issue, the negotiator could call the Vice President and get clarification. If the letter was truly a fraud then what would be the end game? Not closing? I don't understand why banks are making the process more difficult than it has to be. In this case, it ended up being an acceptable offer and went to closing.

Read more…

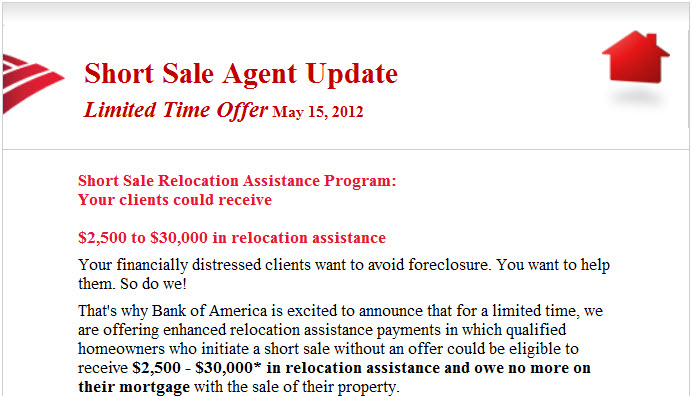
If you have a home loan through Bank of America and you are currently concerned about making your payments or your home is worth less than you owe, you may qualify for a short sale incentive from BoA. They refer to it as an 'enhanced relocation assistance payment'. To qualifying home owners/sellers, this could mean a check given to you for up to $30,000 after a successful short sale closing! Trust me, this is no scam. Here is a recent email that was sent to Bank of America Short Sale Specialists, like myself.

BoA Short Sale Incentive at Closing Letter

My name is Michael Collins, real estate agent and broker at Rock Realty. If you are currently considering a short sale in Wisconsin, I would be happy to walk you through the process and answer any questions you may have. I am certified as a Short Sales & Foreclosure Resource through the WRA.

Realtors® who have earned the SFR certification know how to help sellers maneuver the complexities of short sales as well as help buyers pursue short sale and foreclosure opportunities. The certification program includes training on how to qualify sellers for short sales, negotiate with lenders, protect buyers, and limit risk. Call my cell at 608-921-8536 and we can see if you qualify for any of these incentives.

Is a Short Sale right for My Home?Also feel free to fill out our simple
Short Sale Home Evaluation Form

Additional Short Sale Information

Read more…

First I must say, I am glad to be part of the Short Sale Superstars site.

I am currently working with two first-time homebuyers. Both of them have offers in on short sales.  One was with B of A and just finally got approved today (over 5 months...gee wez), the other one was with Wells Fargo who move much faster (less than 3 months). Not very often I get that good of news in the same week. I currently have one short sale listing in Fullerton, CA and their loan is also with B of A.  This poor seller has had 4 buyers drop out due to B of A taking so long. The week isn't over yet, maybe I can have three this week and the 5th buyer on this property will be the lotto winner.  A new record for me. Keep you posted.

Read more…

Blog Topics by Tags

Monthly Archives

********************************** like buttons ************************